
Are You Overinsured or Underinsured? Signs Your Coverage No Longer Fits Your Lifestyle
Key Takeaways
- Many Malaysians have out-of-date insurance coverage. A 2026 survey found 59% of Malaysians feel adequately insured, yet only 35% could sustain their lifestyle beyond six months without income.
- Being underinsured does not mean having no coverage at all. It often means your policy has not kept up with your financial responsibilities, your risks, and overall inflation.
- Being overinsured is also a real thing. One-third of Malaysian policyholders report overlapping or unnecessary coverage, and 7% feel they carry more than they need.
- Life events like marriage, a new child, a new mortgage, or a salary jump are the most common reasons a policy no longer fits. The plans rarely get updated when these happen.
- A coverage gap can sit quietly in a policy for years. You often only find it when you are trying to make a claim.
Introduction
Whether it is out of genuine need at one point, a recommendation by a neighbourhood auntie, or simply to support an insurance agent friend, many Malaysians have bought an insurance policy at one point in life and just left it until they eventually need it. The premium is renewed every year, but the coverage stays the same. Meanwhile, salary, family size, and medical costs have all moved on.
A 2026 survey by a licensed Malaysian insurer found that 59% of Malaysians believe they are adequately covered, but only 35% could actually keep up their lifestyle for more than six months if their income stopped. That gap is what being underinsured in Malaysia actually looks like in practice. This is what an insurance policy review in Malaysia is supposed to fix.
What Does Being Underinsured in Malaysia Mean
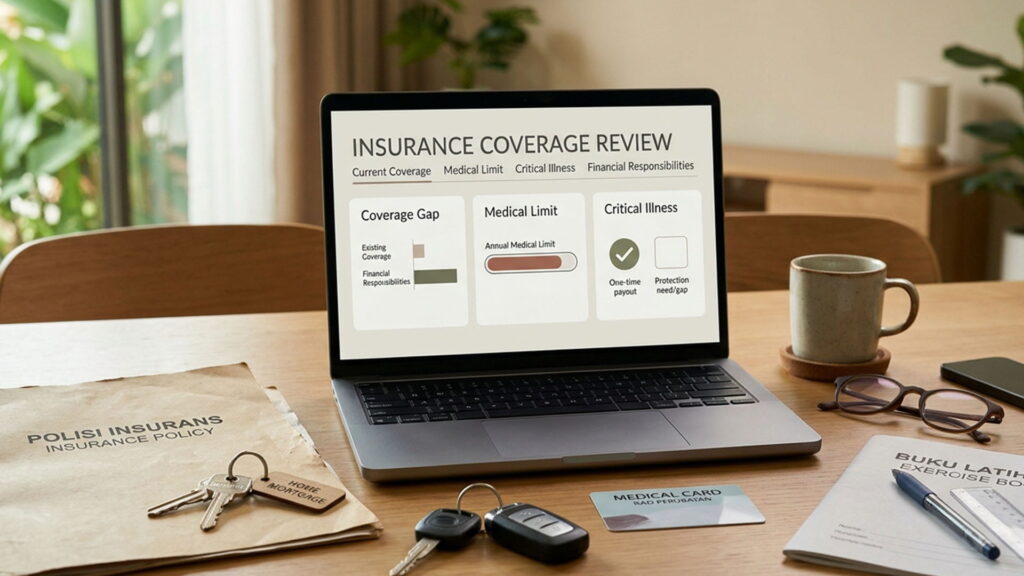
Essentially, being underinsured means that the payout or the coverage provided by the insurance policy falls short of your actual financial needs at your current life stage. This includes replacement costs, medical expenses, or compensation for permanent disabilities. Some examples are as below:
1. Your Coverage Does Not Reflect Your Financial Responsibilities
When you first bought that policy, it could be before you got married, before the mortgage, before the kids, and before your income grew. As your commitments grow and salary increases, a policy that was designed for an entry-level salary will not be able to sustain current lifestyle needs for long.
- Your Medical Card Has an Insufficient Annual Limit
With Malaysia’s medical inflation running at 16% in 2026, cancer treatment, a major surgery, or a long hospital stay can easily deplete your annual claim limit faster than you would expect.
3. Your Critical Illness Plan Only Pays Once
It is worth noting that while the coverage provided by some Critical Illness plans may seem extensive, many only pay once upon triggering the claim. Say you are diagnosed with a disease when you’re 48, and your coverage pays out in full. If you then face, say, another different illness years later, you would not receive another payout.
Signs You Are Overinsured in Malaysia
Essentially, being overinsured means that you have more insurance coverage than necessary. Although it’s generally better to be safe than sorry, being overinsured means that you could be paying for redundant coverage with no additional benefits. This results in wasted money as the additional premiums could have gone towards building additional retirement funds, children’s education fund, or even just spent on lifestyle. It is also not uncommon to be overinsured. The same 2026 survey found that one-third of Malaysian policyholders have overlapping or unnecessary coverage, and 7% feel they carry more than they actually need.
Common scenarios of overinsurance in Malaysia include:
1. Having multiple insurance plans that provide similar coverage
One way of being overinsured is when you hold multiple policies or add-ons that cover the same risks that cannot be claimed simultaneously. A simple example would be having multiple personal medical and hospitalisation plans. These plans will not pay out if another insurance coverage (e.g., company medical coverage) has already paid your claim.
2. Having Add-Ons that You Do Not Require
Generally, insurance is a contract where you receive a financial payout when the trigger event or loss occurs. This can include losing bodily function due to a debilitating accident, or losing your job because of a medical condition. However, there are occasions where the policies come with riders or add-ons that you do not need.
For example, many life insurances today already come with comprehensive life and disability protection; therefore, having an extra accidental death and dismemberment rider can be redundant.
3. Life Cover That Has Not Been Adjusted for Your Current Stage
A policy that is designed for a young family will be much different from what you need once the mortgage is nearly paid for and the children are already working. Not adjusting your policy to match your current life stage means that you could likely be overpaying for coverage that is already obsolete.
Life Events That Should Trigger an Insurance Coverage Review
Most of the time, a policy falls short because you have moved on to another stage of life, but you did not update your coverage. Here are life stages where a review of your insurance coverage is worth considering:
1. Getting Married or Having Children
Whenever you reach a stage where you welcome an addition to your household, it is worth evaluating your additional financial responsibilities, if any, and then reviewing your insurance policies. It could be as simple as adding them as beneficiaries to your existing policies or acquiring additional coverage to ensure your family’s living costs are taken care of.
2. Career Changes
A career change usually also comes with a change in financial status. Whether it is a promotion, retirement, or leaving your job to be your own boss, any career change may require new financial decisions to be made. With an increase in salary and more expandable income, you might want to consider that your sum assured matches your growing lifestyle needs. On the flip side, if you have just lost your job, you may want to consider downgrading your policy or adjusting your premiums to a more manageable figure.
3. Protecting a Major Family Expense
Is your family home still under mortgage? Did you just buy the family car? If you are supporting these important family assets, you may want to evaluate whether your coverage can support these expenses when you are no longer around. You do not want to burden your family if possible.
How to Do an Insurance Policy Review in Malaysia
Before you call anyone, sit down and figure out what you actually have.
Pull out every active policy you have. For each one, note the annual premium, the coverage terms or maturity dates, and of course, the amount and type of coverage. Then write out your current situation: monthly household expenses, outstanding loans, how many people depend on your income, and what you earn now.
The next step is to consider the following:
1) Is your current coverage able to meet what your family would need if you were gone or unable to work? How many years would this cover?
2) Is the annual limit of your medical insurance able to cover the cost of a serious operation or a long hospital stay?
3) Does the payout of your insurance plan reflect your lifestyle needs and obligations at your current life stage?
If you are unsure about where to begin or simply do not want to go through the hassle of poring over documents filled with technical terms and financial jargon, the Uno Advisers’ financial planning team is more than happy to assist you. Our team is equipped with the know-how and experience to assess your insurance coverage and advise you on the proper measures to take to ensure that you are adequately protected.
Frequently Asked Questions
1. How do I know if my coverage no longer fits my lifestyle?
Your life cover amount has not changed since you were single. Your medical annual limit has not kept up with hospital costs. Your income replacement is based on a salary you earned years ago. You have a mortgage but no policy mapped to it. If any of those sound familiar, your coverage probably does not reflect where you are now.
2. What does being underinsured actually mean in Malaysia?
It means the coverage you hold exists, but it does not go far enough. Even households with both life and medical insurance have an average protection gap of RM553,000. That is not a figure for people without insurance. It is for people whose insurance would not actually cover what their family needs.
3. When should I do an insurance coverage review?
After any major life change: marriage, a new child, a mortgage, a salary increase, or leaving a job. Outside of that, every two to three years is reasonable. Medical costs in Malaysia rose 16% in 2026, so coverage from a few years ago buys less protection today.
4. What does being overinsured in Malaysia actually look like?
It tends to look like multiple policies slowly accumulating without anyone checking whether they still make sense together. Two plans covering the same risk. Riders covering risks you are not exposed to anymore. A 2026 survey found one-third of Malaysian policyholders report overlapping or unnecessary coverage.
5. Is a coverage review the same as being sold a new policy?
Not at all. A proper review starts with what you already own. The goal is to understand whether it still fits your life. Sometimes something needs topping up. Sometimes you are paying for more than you need. An insurance optimisation review is designed to answer that honestly.
So, are you overinsured or underinsured? The honest answer is probably somewhere in between. Some coverage may not have been updated since you first bought it. Some policies may have overlaps that you are not aware of. An insurance optimisation review with Uno Advisers is the practical way to identify possible gaps in your protection coverage.