
How Close Are You to Becoming a Millionaire by 60?
Key Takeaways
- Retirement wealth planning in Malaysia has a clear benchmark: EPF’s three-tier Retirement Income Adequacy Framework puts RM390,000 as the Basic Savings level, RM650,000 as Adequate Savings, and RM1.3 million as Enhanced Savings.
- The biggest factor in whether you reach RM1 million and above is more than just salary. It is also very important how early you start and how much time your money has to grow.
- How early you start is equally important to how much you save. The maths of compound interest in Malaysia is stark: assuming a 5% annual rate of return, someone starting to invest at age 25 needs to set aside RM880 monthly to reach RM1 million by age 60. Whereas someone only starting at age 45 will need RM3,740 monthly, over four times more.
- EPF is part of the picture and should not be solely relied on for your retirement savings. Adding investment vehicles such as stocks, exchange-traded funds (ETFs), unit trusts, or Private Retirement Schemes (PRS) can meaningfully increase your asset growth over time.
Introduction
Many people dream of becoming a millionaire, and while it may seem unachievable, having RM1 million by the time you retire can become more realistic with enough time, discipline, and well-planned financial strategies.
This article covers what RM1 million means at retirement, what the numbers look like at different starting ages, and how to check where you currently stand. Good retirement wealth planning in Malaysia just needs to start with the right question: how close are you, and what can you do to close the gap?
How Much Is RM1 Million Worth During Your Retirement in Malaysia?
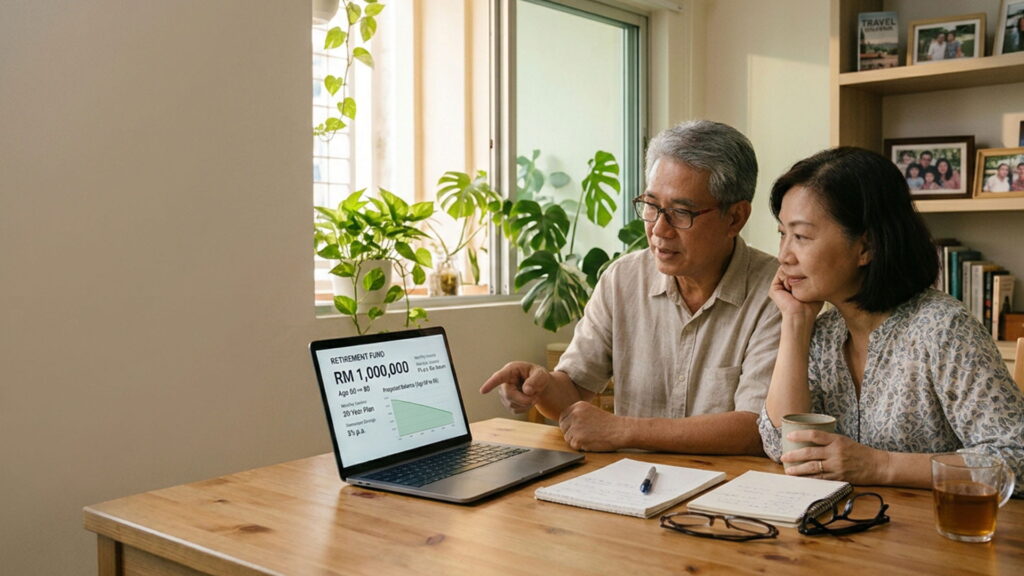
We have two approaches to this: first is if you only utilise the returns from the RM1 million as your living expenses. The second is if you plan to deplete the RM1 million over the course of your retirement.
Assuming a 5% p.a. rate of return, the first method yields RM50,000 a year in returns, which equates to about RM4,100 monthly.
The second method, assuming the same rate of return and a 20-year retirement lifespan from age 60 to age 80, will allow you to spend approx. RM6,600 monthly.
Based on the projections above, having RM1 million in retirement savings means that you should be able to live an acceptable standard of living in the Klang Valley. Moderate, with the occasional luxury.
A 2026 survey by a licensed Malaysian insurer found that 46% of respondents felt their retirement savings were not on track, and with rising costs of living as financial priorities have shifted towards more immediate needs, leaving longer-term goals deprioritised.
How Compound Interest Works in Malaysia Over Time
With expenses and inflation on the rise, it is safe to say that relying entirely on your bank savings is inadequate for you to sustain your lifestyle for long after retirement. However, by putting the money to work and accruing compounding interest through investing, over time, you will be able to see your savings multiply, making that millionaire dream much closer than you once perceived it to be.
Here’s a simple calculation on how compounding interest works over time. Let’s take an annual return of 5%, which is more conservative than EPF’s 2025 dividend rate of 6.15%. To reach RM1 million by age 60: requires investing RM880 monthly if you start at age 25, or RM3,740 monthly if you only start at age 45. Same destination but starting at age 40 requires over four times the monthly commitment. Same destination, but five times the monthly commitment depending on when you start.
The calculation above clearly depicts how starting early and giving your money time to grow can accelerate wealth through compounding interest. This is really what reaching RM1 million by retirement comes down to: not just how much you save, but how long that money has to grow and where it goes.
What Builds Your Wealth Alongside EPF
EPF is a good foundation to start. For salaried workers, the contributions are automatic, yearly returns have been relatively consistent, and it keeps you from spending the money before retirement. However, depending solely on EPF for your retirement savings risks leaving you financially short, as all your risk depends on the sustainability of EPF’s dividend rate. Additionally, what if you decide to retire before age 55? You would then be unable to utilise your retirement fund.
Therefore, for anyone serious about retirement wealth planning in Malaysia, the real approach when it comes to wealth accumulation in Malaysia is to diversify your investments and build on what EPF provides. This guide to low-risk investments in Malaysia covers options worth considering alongside EPF.
Below are some common investment instruments that you can look into to start diversifying your investment portfolio.
Investments in Stocks
First off, you can choose to invest in individual shares through Bursa Malaysia or through local brokerages that open up investment opportunities in global markets. Capital gains on locally listed shares are generally not taxed for individual investors in Malaysia, which is a real advantage for long-term holders. The FBM KLCI averaged around 4% a year over the past decade. However, one downside to consider is that individual stock investing can take up a lot of time and effort, as it requires in-depth study and understanding of financial statements, industries, and market trends. Also, investing in individual stocks can be pretty volatile, so you need to be patient and emotionally disciplined to reap the benefits.
Exchange-Traded Funds (ETFs)
If poring over financial reports and keeping tabs on the stock market daily is not for you, an alternative investment vehicle you can consider is exchange-traded funds, more commonly known as ETFs. ETFs enable you to invest in a basket of companies through a single trade. Bursa currently lists roughly 13 to 20 ETFs covering Malaysian equities, global indices, bonds, and commodities, including Shariah-compliant options. You can also access global ETFs through local brokerages. However, one thing to note is that the ETFs each follow their own predetermined system of stock selection, which means you will not be able to pick and choose your favourites.
Unit Trusts
A unit trust is a collective investment scheme where money from many investors is pooled together to invest in a diverse portfolio of assets including bonds, stocks, and money market instruments. Unit trusts are managed professionally through professional fund managers. Unit trusts are popular amongst Malaysians because they require lower initial investment and do not require high in-depth monitoring. However, unit trusts typically incur some higher fees, which can eat into your returns.
Private Retirement Scheme (PRS)
Apart from the options above, you can also opt for PRS as an additional instrument to grow your retirement savings. A benefit that PRS offers is that individuals who contribute to a PRS are eligible for personal income tax relief of up to RM3,000 every year. However, similar to EPF, funds in Private Retirement Schemes are locked until age 55 with a penalty for early withdrawals, so it is not the most flexible option. A PRS fund is very similar to a unit trust in its structure.
Are You on Track for Your Retirement Savings Goal in Malaysia?
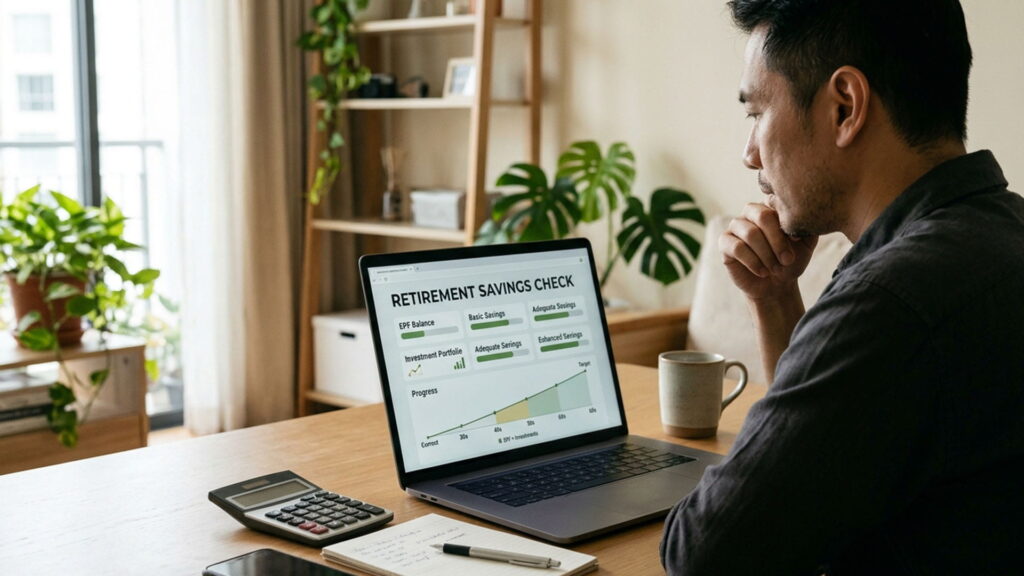
You can use EPF’s recommended basic tier savings as your floor numbers. Open your EPF portal or app and check on your balance. If your balance is above the Adequate or Enhanced savings levels for your age, and you have other investments growing your wealth, you are heading in the right direction.
However, if your EPF and investment balances are below par, do not panic. This is an indication that you should pick up the pace and start exploring investment options to grow your wealth.
Unfortunately, making sound investing decisions can be harder than you expect. With so many investment opportunities out there, how do you know which one suits you best? How do you know how much you should also be investing monthly? Also, there could be a risk that you may fall victim to scams and Ponzi schemes if you are unfamiliar. This is where engaging a financial planner can be worthwhile. A financial planner will have the expertise to assess your financial standing and advise the right investment strategies for you based on your personal needs.
Frequently Asked Questions
1. How close am I to becoming a millionaire by age 60?
It depends on what you have saved, your age, and what your money is currently earning. Someone with RM100,000 at age 35 would need to invest RM1,100 monthly at a rate of 5% p.a. to reach RM1 million by age 60. At higher returns through stocks, unit trusts, or ETF investing, that monthly amount could be lower. The only way to know your real position is to look at your actual numbers.
2. Is RM1 million enough to retire comfortably in Malaysia?
While it will not provide a fully luxurious standard of living, it is still a meaningful amount. RM1 million can sustain a RM4,100 monthly living expense if you are just living on the returns, leaving the capital untouched. If you are depleting the capital over 20 years, you can sustain a higher lifestyle of about RM6,600 monthly. Whether that is comfortable enough for you will depend on where you live and what kind of lifestyle you lead.
3. How do I know if I am on track to reach RM1 million by age 60?
Check the EPF RIA Adequate and Enhanced Savings benchmarks for your age. Then check your EPF balance and add any investments you have outside EPF. If the combined total is above somewhere between those benchmarks, preferably closer to the enhanced savings number, then you are on track. If EPF is all you have and you are below those numbers, your retirement wealth planning in Malaysia needs a rethink, and the sooner the better.
4. Does compound interest really make that big a difference in Malaysia?
Yes, and the difference is larger than many people expect. This is what the maths of compound interest in Malaysia shows clearly: at a 5% rate of return, starting at age 25 instead of age 35 roughly halves the monthly amount you need to reach RM1 million by age 60. Starting at age 45 means over four times the monthly commitment compared to starting at age 25. The earlier you start building wealth in Malaysia, the less heavy lifting each ringgit has to do.
5. What should I do first if I want to reach RM1 million by 60?
Find out where you are right now. Pull up your total assets, EPF plus other investments and savings. Then, compare it against the RIA Adequate and Enhanced savings benchmarks for your age, and see where you stand. Once you know this, then evaluate how much you can set aside for additional investments each month. Finally, you can make a proper decision on where to allocate your money: stocks, unit trusts, PRS, ETFs, a combination, or other solutions. The retirement planning team at Uno Advisers can work through it with you for even greater clarity.
So how close are you to becoming a millionaire by age 60? The answer is often more achievable than you expect once you see the full picture. Solid retirement wealth planning in Malaysia means knowing where you are and building from there. Uno Advisers offers retirement planning built around your actual numbers, so you can see what it takes to reach RM1 million from where you stand today.